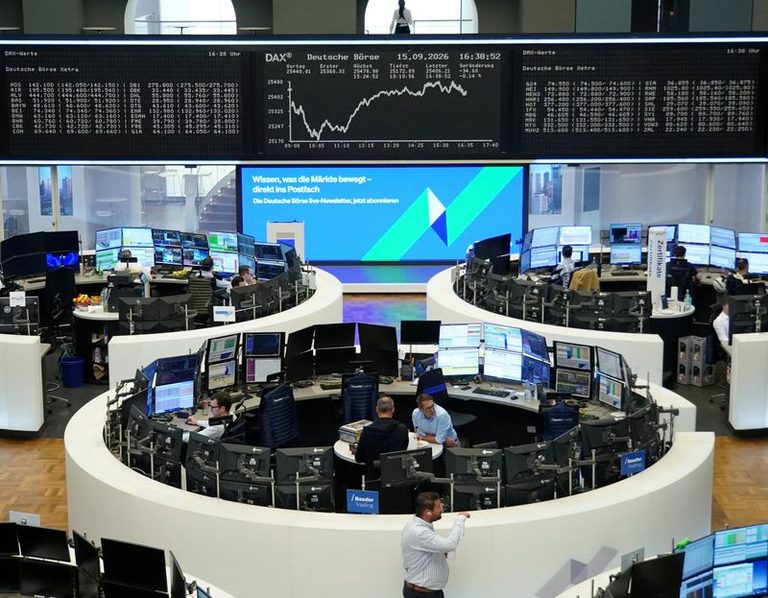
European equity markets showed a modest recovery on Wednesday, reversing two days of declines as the rally in oil prices paused. The pan‑European STOXX 600 index rose 0.4% to 636.81 points by 0705 GMT, while Germany’s DAX also gained 0.4%.
Fed decision dominates market sentiment
Trader attention is now fixed on the U.S. Federal Reserve’s monetary‑policy decision later in the day. Market pricing, based on the CME’s FedWatch tool, indicates a 93% probability that the Fed will raise its benchmark interest rate by a quarter‑point.
Rising inflation pressures stemming from the conflict in Iran have prompted investors to reassess expectations for future rate moves, keeping the outlook for higher rates alive.
Oil price pullback lifts risk‑sensitive stocks
Crude oil prices eased on Wednesday, slipping 0.6% after a recent surge. The dip helped stocks most affected by higher energy costs to rebound, with banks leading the gains. Barclays and Standard Chartered posted increases of 1.4% and 1.7% respectively.
These financial‑sector advances helped pull the STOXX 600 out of a three‑month low that had been reached on Tuesday.
Company news highlights
British defence and engineering firm Babcock International maintained its annual outlook, with shares climbing 2.5%.
Home‑builder Barratt Redrow announced a trimmed target for home completions in fiscal 2027, citing planning delays and fewer sales‑outlet openings. Despite the revised guidance, the company’s stock rose 5.1%.
Outlook
Investors will watch the Fed’s decision closely, as any change in the rate path could influence both European equity markets and global risk appetite. The current market sentiment suggests a cautious optimism, with the expectation that a modest rate hike will keep inflation pressures in check while allowing equities to maintain their recent gains.
Original reporting: Appleton, WI News Feed (HLL/CB) — read the source article.