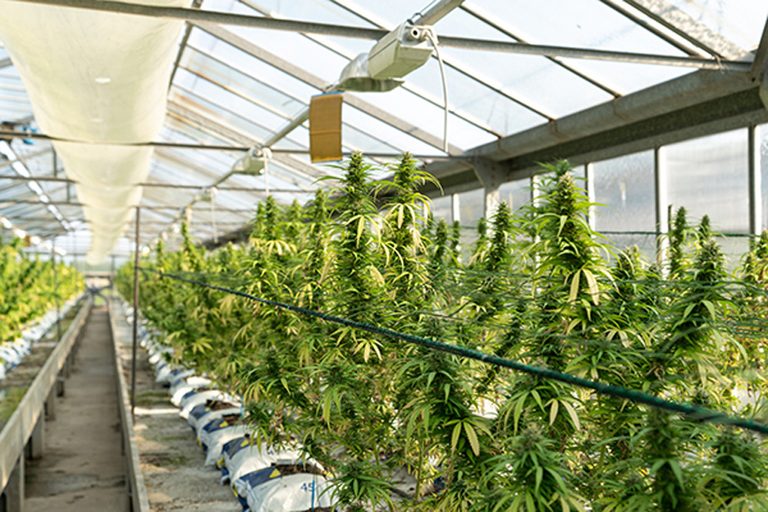
On Oct. 1, Connecticut’s legislature enacted Public Act 26‑68, shifting the state’s cannabis tax from a potency‑based excise to a flat‑rate 10.75% levy on gross receipts. The change is intended to simplify the tax structure, but the state’s own Office of Fiscal Analysis (OFA) projects a shortfall.
Projected revenue impact
Using tax collections and retail‑sales data from Jan. – May 2026, the former THC‑based tax generated roughly $2.8 million to $3.4 million per month. Applying the new 10.75% rate to the same sales volume would yield about $1.9 million to $2.2 million per month – an average monthly loss of roughly $1 million.
OFA estimates the annual loss at $1.9 million for fiscal year 2027, $2 million for FY 2028, and $2.1 million for FY 2029, with the shortfall stabilizing around $2.2 million per year thereafter.
Why price trends matter
Under the old system, a decline in product price did not directly reduce tax revenue because the tax was tied to THC content, not sales price. The new system ties the tax to gross receipts, so falling prices will require higher sales volume to offset the lower tax base.
Connecticut’s cannabis market has already seen price compression. If prices continue to drop, the state will need sufficient growth in taxable sales to prevent further revenue erosion.
Impact on equity funds and municipalities
The Social Equity and Innovation Account, which receives a share of cannabis‑tax revenue, is temporarily insulated. Public Act 26‑68 raises its share from 65% to 70% for FY 2027‑2028 while cutting the General Fund’s share from 10% to 5%.
However, OFA projects that beginning FY 2029 the equity account will lose about $1.6 million annually, rising to roughly $1.7 million thereafter. Municipalities continue to collect a 3% tax on gross receipts, but they too could feel the effects if market prices and sales volumes decline.
Questions for lawmakers
The analysis highlights a key unanswered question: how much additional sales volume will be required to offset falling prices and the lower tax rate? Lawmakers have not disclosed the assumptions used for future price trends, sales‑volume growth, or price‑elasticity.
Stakeholders argue that the state should model these scenarios before the tax change takes effect, ensuring the cannabis market can reliably fund public priorities and equity initiatives.
What’s next
Connecticut’s cannabis industry remains in a formative stage. The tax shift represents a significant policy experiment that will test whether the market can generate enough gross receipts to sustain the projected revenue stream.
As the first fiscal year under the new tax begins, the state will closely monitor sales data, price movements, and tax collections. The outcome will inform whether further adjustments are needed to protect both the General Fund and the Social Equity and Innovation Account.
Original reporting: The Connecticut Mirror — read the source article.