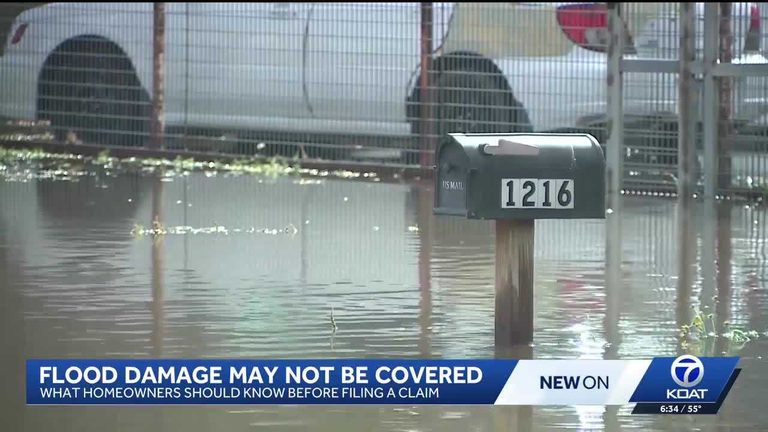
With recent heavy rainfall sweeping across New Mexico, the state’s Office of the Superintendent of Insurance (OSI) is warning homeowners that most standard homeowners’ policies do not include flood coverage. While many policies will pay for rain‑related roof damage, they typically exclude flooding, water‑borne debris, and runoff that can occur near recent wildfire burn scars.
What’s covered and what isn’t
According to OSI, a typical homeowners’ policy will cover damage caused by rain that directly impacts a roof or interior, provided the loss falls within the policy’s deductible. However, the same policy will not pay for water that flows over the ground, rises from the soil, or carries debris from a burn scar. Those types of losses are classified as flood damage.
Separate flood insurance is available
Homeowners who need protection from flood‑related losses must purchase a separate flood insurance policy. These policies are backed by the Federal Emergency Management Agency (FEMA) and are available even for properties that lie outside federally designated flood zones. The separate policy can be bought through private insurers that participate in the National Flood Insurance Program.
Advice from OSI officials
Melissa Robertson, OSI’s property and casualty bureau chief, emphasized the importance of confirming coverage before filing a claim. “Homeowners can file claims for their roof,” Robertson said, “but if their home is sitting below a burn scar, they need to realize that the water flow, the debris flow is not something that is covered.” She urged residents to contact their insurance agents, compare deductibles with repair estimates, and consider adding flood coverage if they live in vulnerable areas.
Legislative action on the horizon
Robertson also disclosed that the state insurance superintendent is working on legislation that could expand coverage to include flooding and debris flows resulting from wildfires. While details of the bill are still being drafted, the effort reflects growing concern that climate‑related events are increasing the risk of flood damage in the state.
Immediate steps to protect your home
In addition to reviewing insurance policies, OSI recommends practical measures to limit further damage after a storm. Homeowners should cover any damaged roof sections with a tarp to prevent water intrusion, clear gutters and downspouts of debris, and move valuables and furniture away from areas prone to water accumulation.
Why this matters for New Mexico families
New Mexico’s families rely on the stability of their homes as the foundation of community life. Understanding the limits of standard insurance and taking proactive steps can help protect that foundation from the financial strain of unexpected flood damage. By staying informed and considering a separate FEMA‑backed flood policy, homeowners can safeguard both their property and their peace of mind.
Original reporting: KOAT Albuquerque — read the source article.