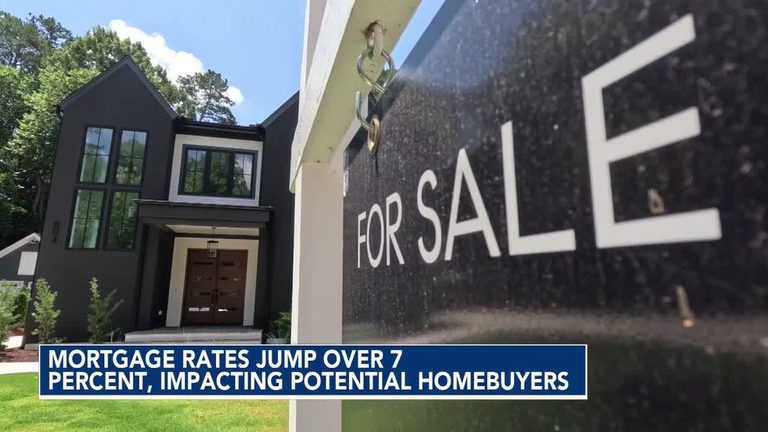
Mortgage rates have surged past the 7% mark, reaching their highest level since May 2024, according to the Mortgage Bankers Association (MBA). The rise is adding significant pressure on homebuyers and current homeowners considering refinancing.
Application activity declines
The MBA reported that mortgage applications fell 1.5% from the previous week as rates increased. Refinance applications dropped 3% for the week and are down 62% compared with the same time last year, indicating that higher rates are discouraging borrowers from seeking new loans or refinancing existing mortgages.
Impact on monthly payments
Higher mortgage rates can add hundreds of dollars to a homebuyer’s monthly payment, depending on the size of the loan. For many families, this increase translates into a tighter household budget and may delay plans to purchase a home.
Broader economic context
The rate increase comes amid elevated inflation and rising oil prices, which have surged since the start of the conflict in Iran. The Federal Reserve also raised interest rates last week. While the Federal Reserve does not set mortgage rates directly, its policy decisions influence bond markets, including the 10‑year Treasury yield, which in turn affect mortgage rates.
Housing market slowdown
Higher rates are adding pressure to the housing market. Sales of previously occupied homes have declined for three consecutive months, reflecting reduced buyer activity as financing costs climb.
Local advice for buyers
Local real‑estate agent Tom Finigan suggested that buyers can still look for ways to reduce costs. He recommended negotiating closing‑cost reductions or points off the mortgage. “The real win would be to negotiate either closing costs from your lender or points off the mortgage because while you may save $5,000 to $10,000 off the front line of the house, if you have a mortgage rate reduction paid for by the seller, you could save hundreds of dollars every month,” Finigan said.
Refinancing and adjustable‑rate options
Finigan noted that refinancing remains an option for homeowners, but rates would need to fall before it becomes attractive for many borrowers. He also observed a growing interest in adjustable‑rate mortgages (ARMs); applications for ARMs now account for nearly 10% of the mortgage market, according to the MBA.
Looking ahead
Analysts will continue to watch Federal Reserve policy, inflation trends, and global events for clues about future mortgage‑rate movements. In the meantime, prospective buyers and current homeowners are advised to explore cost‑saving strategies and consider the long‑term implications of higher financing costs.
Original reporting: WRAL Raleigh — read the source article.