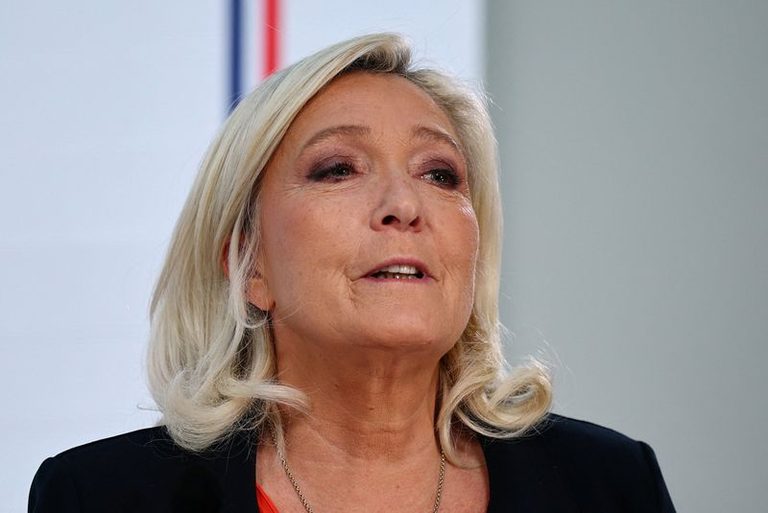
In a recent interview with Reuters, Mike Bell, head of market strategy at RBC BlueBay Asset Management, said the market’s next move on French sovereign debt hinges on whether Marine Le Pen, the leading candidate of the National Rally, will pledge to raise the retirement age. Bell explained that investors are watching the upcoming presidential election closely, and a clear policy signal could ease pressure on France’s borrowing costs.
Why the retirement age matters to bond markets
France’s public finances are already strained, with pensions accounting for €436 billion next year – roughly 14% of the nation’s economic output. Historically, French politicians have been hesitant to raise the retirement age because it can hurt pensioners’ purchasing power, and older voters form a key constituency for Le Pen’s party.
Bell warned that if a candidate who keeps the retirement age at its current level appears likely to win, the yield premium that investors demand for holding French 10‑year bonds over German Bunds could widen to as much as 200 basis points. The spread already rose above 150 basis points last Friday, its highest level since late 2011.
Le Pen’s current position
Le Pen has previously supported cutting the retirement age to 60 for those who began working early, but she has not yet detailed any pension reform in her budget outline released on Tuesday. She indicated that specific proposals would be presented in the coming weeks.
RBC BlueBay holds a modest amount of French bonds but is not overweight the market. Bell said it would take a “brave person” to increase exposure before the election, which is scheduled for April 18‑May 2, 2027.
Potential clash with the European Central Bank
France currently has one of the lowest retirement ages among advanced economies – 62.9 years, depending on birth year – and the longest life expectancy. The government suspended a 2023 reform that would have gradually raised the age to 64 in order to secure passage of the 2026 budget.
Bell cautioned that a Le Pen victory could set up a confrontation with the European Central Bank (ECB). He noted, “I struggle to see a world in which a fervent French nationalist takes kindly to being told by the ECB what they need to do to contain borrowing costs.” He added that some officials in Brussels may view high French yields as leverage to push the next president toward stricter fiscal discipline.
Risks of short‑selling French bonds
While some investors might consider short‑selling French sovereigns to profit from further yield rises, Bell warned that much of the risk is already priced in. He emphasized that any aggressive positioning carries significant downside if the policy outlook improves.
Overall, the market is awaiting a clear signal from the leading presidential hopeful. A commitment to raise the retirement age could help narrow the yield spread, lower borrowing costs, and reduce pressure on France’s already fragile public finances.
Original reporting: Appleton, WI News Feed (HLL/CB) — read the source article.