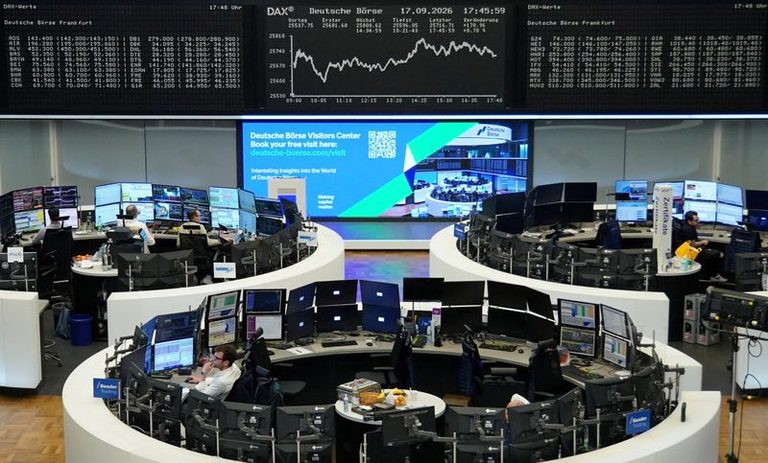
European equity markets showed a slight pullback on Friday, with the broad‑based STOXX 600 index slipping 0.2% to 641.57 points by 0717 GMT. The decline came after the index had risen more than 1% over the previous two sessions, hovering near one‑week highs.
Telecoms and energy lead the losses
Telecommunication stocks were the biggest drags, falling 1.8% early in the session. Germany’s Deutsche Telekom dropped 3.1%, while Airtel Africa slid 4.8%, reflecting investor concerns over sector earnings and regulatory pressures.
Energy shares also moved lower, shedding 0.5% as oil prices fell for a third consecutive day. Prices remain above the $100‑per‑barrel threshold, but market sentiment was dampened by hopes that Saudi supply disruptions would be limited.
Food, beverage and tech provide mixed signals
Food and beverage stocks lost 1%, with Nestlé down 1.2% after Russia seized control of the Swiss company’s local assets, adding geopolitical risk to the sector.
On the upside, technology stocks rose 0.9%, led by chip makers Aixtron and Infineon Technologies, which helped offset some of the broader market weakness.
Central‑bank backdrop
The market’s movement occurred against a backdrop of major central‑bank decisions. The U.S. Federal Reserve, the Bank of England and several other central banks announced interest‑rate actions, contributing to a mixed outlook for investors.
Despite the modest dip, the STOXX 600 remains on track for its first weekly gain in three weeks, suggesting that the market may still find footing as investors digest the latest policy signals and commodity price trends.
Outlook
Analysts will be watching upcoming economic data and further central‑bank guidance for clues on whether the recent gains can be sustained. For now, the market appears to be balancing sector‑specific pressures with broader macro‑economic developments.
Original reporting: Appleton, WI News Feed (HLL/CB) — read the source article.