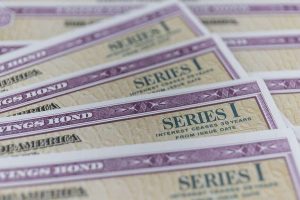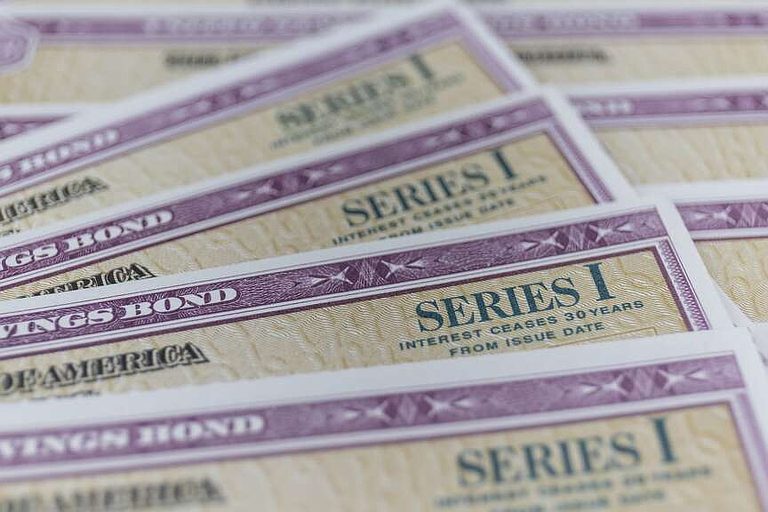
The U.S. Treasury has raised the combined annual rate on newly issued Series I Savings Bonds to 5.51% for the next six‑month period. The rate consists of a 1.40% fixed base component and a 4.08% inflation adjustment, the highest inflation adjustment since May 2022.
How the rate is calculated
The inflation adjustment is updated every six months on May 1 and November 1 based on changes in the Consumer Price Index. When added to the fixed base rate set at the time of purchase, it determines the headline annualized yield that bondholders will receive.
Recent history of I‑bond yields
Purchases made through October 31 carried a 4.26% combined rate. Earlier, in May 2022, the fixed base rate was zero and the inflation adjustment produced a 9.62% annualized yield, prompting a surge of online purchases via TreasuryDirect.gov. As inflation moderated, subsequent six‑month periods saw rates fall to 3.24% and then to 1.69%.
Fixed base rate evolution
The fixed base rate remained at zero from 2020 through May 2022. It increased to 0.4% in November 2022, rose to 0.9% later that year, and now stands at 1.40% for bonds sold today. This fixed component provides a cushion if future inflation adjustments decline.
Is an I‑bond right for you?
Series I Savings Bonds are designed for investors who can hold the bond for at least five years to avoid a three‑month interest penalty and for a minimum of one year before redemption. They offer inflation protection and tax advantages: interest is deferred until redemption and is exempt from state income tax.
Investors seeking greater liquidity may consider six‑month Treasury bills, which return principal at maturity, or Treasury‑only money market funds, which typically offer slightly lower yields but allow access to cash at any time.
How to purchase
Bonds can only be bought through the TreasuryDirect website. Buyers must create an account using their Social Security number, provide bank routing and account numbers, and adhere to a $10,000 annual purchase limit per Social Security number. Spouses must open separate accounts, even when funding a joint purchase. Gifts can be made using the recipient’s Social Security number or by holding the bond in the giver’s account for later transfer.
There is no provision for purchasing I‑bonds within an IRA, and the annual limit applies to each Social Security number, not to joint accounts. Additional purchases can be made through a revocable living trust that obtains its own Employer Identification Number.
Interest payment schedule
Interest is not posted to the TreasuryDirect account until the fifth month after purchase, reflecting the three‑month penalty for early redemption. After the first six‑month period, interest accrues at the announced rate and is credited semi‑annually.
For investors prioritizing safety, inflation protection, and a long‑term horizon, Series I Savings Bonds remain a viable option despite the inevitable rate fluctuations tied to inflation trends.
Original reporting: Texarkana Gazette — read the source article.