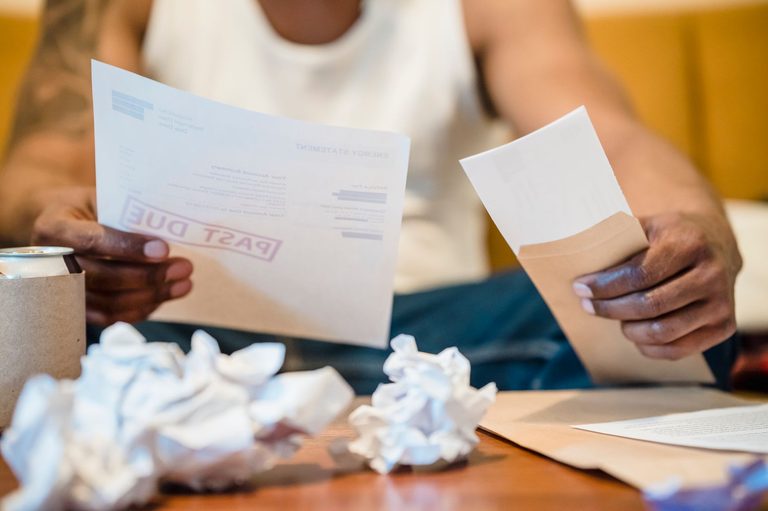
Consumers across the United States are feeling the squeeze as household debt climbs far faster than wages. The Century Foundation, a progressive independent think tank, released a report indicating that debt payments are rising eight times as fast as take‑home pay. As a result, workers are losing 52 cents of every dollar earned to service debt.
Debt Burden Varies by Race and Gender
The report highlights that racial and gender wealth gaps exacerbate the problem. People of color often face higher interest rates on credit cards and auto loans, meaning a dollar of debt costs more to service. Among super‑prime borrowers, Black workers’ debt payments still consume 13.6% of take‑home income, compared with 8.4% for white workers. These gaps appear across all credit tiers and income quintiles.
Rising Interest Rates and Credit Card Costs
Credit‑card interest rates have surged from 12.90% in 2013 to 22.8% in 2023, the highest level on record. The report notes that workers whose paychecks already fall short are now spending billions each year on interest alone. Experian data shows the average credit‑card rate sits at 19.25%, with a range from 7.9% to 34.52% depending on card type, issuer, and promotional terms.
Auto Loans Add to the Strain
Auto loan balances grew by $28 billion to $1.71 trillion nationwide, according to the Federal Reserve Bank of New York. The average monthly payment for a new car is $765, while a used‑car payment averages $542. Interest rates differ dramatically by credit score: borrowers with deep subprime scores (501‑600) face an average rate of 21.62%, roughly three times the 6.29% rate enjoyed by super‑prime borrowers (781‑850).
Delinquency Concerns
Subprime borrowers represent nearly two‑thirds of all delinquent loans, defined as payments at least 90 days late. Of loans originated between 2021 and 2023, 62% were in default by April, with higher debt‑to‑income ratios across all credit categories, according to the Federal Reserve Bank of Philadelphia.
Policy Recommendations
The Century Foundation concludes that rising household debt signals broader economic failures. It calls for a multi‑pronged agenda: debt relief, wage growth, expanded bargaining rights, tighter regulation of predatory lenders, and increased public provisioning to strengthen the labor market.
Expert Commentary
Joelle Scally, economic policy adviser at the Federal Reserve Bank of New York, noted that new delinquencies for auto loans and credit cards remain at elevated levels and will continue to be monitored.
While the report paints a stark picture, it also underscores the importance of responsible lending practices and policies that protect families—especially those already facing systemic barriers—to ensure financial stability for all Americans.
Original reporting: The Washington Informer — read the source article.