Recent data show that Horry County’s real‑estate landscape is no longer dominated by sellers. The overall market now offers more inventory than demand, yet the picture differs sharply between condos and single‑family homes.
Inventory Gives Buyers the Edge
Real‑estate professionals use “months of supply” to gauge market balance. Anything above six months generally favors buyers. Redfin’s mid‑year review placed the Myrtle Beach metro at about 6.2 months of supply for the first half of 2026, up from a seller‑heavy environment in 2021‑2022. The typical home stayed on the market roughly 111 days, about 11 days longer than a year earlier and more than double the national median.
Local broker Greg Harrelson, who has served the Grand Strand for over thirty years, noted a 36 % jump in inventory this summer, confirming the county’s move away from the frenzy of the pandemic‑era.
Condos: A Clear Buyer’s Market
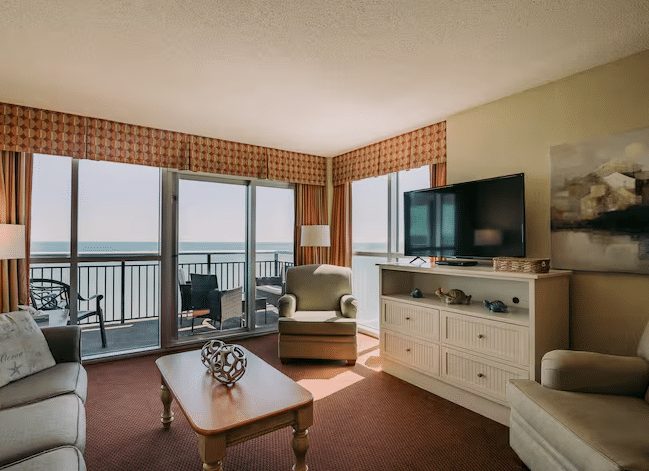
Condominium inventory has risen above eight months, according to the Coastal Carolinas Association of Realtors (CCAR). Median condo prices fell roughly 12 % year‑over‑year to $195,000 in the first quarter, and oceanfront units have seen even softer pricing and longer marketing times.
Three pressures drive this gap:
- Vacation‑rental revenue in the Myrtle Beach area dropped about 20 % over the past year, weakening the investment appeal of oceanfront condos.
- Higher HOA dues, special assessments, and insurance costs increase the ongoing expense for condo owners.
- Many older condo buildings lack the reserves required for conventional financing, limiting the pool of qualified buyers.
For buyers seeking a condo this fall, there is room to negotiate price, repairs, and closing credits.
Single‑Family Homes: Balanced, Not Buyer‑Friendly
Single‑family homes hover just under five months of supply, indicating a balanced market. Prices have remained essentially flat, with Zillow reporting a typical Horry County home value of about $320,000 as of September, unchanged from a year earlier.
Buyers of single‑family homes can find leverage mainly on properties that are overpriced or need significant work.
Location Matters: ZIP‑Code Variations
Countywide averages mask stark differences across ZIP codes. In Carolina Forest (29579), median single‑family prices jumped roughly 20 % to $545,000, while year‑to‑date closings fell about 25 % and new listings declined.
Condo inventory in the same area dropped from 213 units to 152, and average days on market rose to 128, suggesting sellers are pulling back.
Conversely, Loris (northern county) saw a modest 5 % rise in median single‑family prices in August, with inventory returning and activity remaining strong.
Financing Challenges: 7% Mortgage Rates
Freddie Mac’s weekly survey shows the average 30‑year fixed rate climbed above 7 % in late September, reaching 7.40 % by mid‑October—up from about 6.27 % a year earlier.
On a $320,000 home with a 10 % down payment, principal and interest would be roughly $1,994 per month at 7.40 %, compared with $1,777 at last October’s rate. That $217 increase represents about 36 % of the county’s median household income of $66,880 before taxes and insurance.
Coastal insurance adds another $500‑$800 to the monthly escrow, further squeezing buyers.
Bottom Line for Local Buyers
While the overall inventory tilt gives buyers more choice, the high cost of financing and coastal insurance means the market is not a classic buyer’s market for everyone. Prospective condo purchasers have the strongest negotiating position, whereas single‑family home buyers should focus on properties that are overpriced or need repairs and pay close attention to their specific ZIP‑code trends.
Original reporting: MyrtleBeachSC News — read the source article.