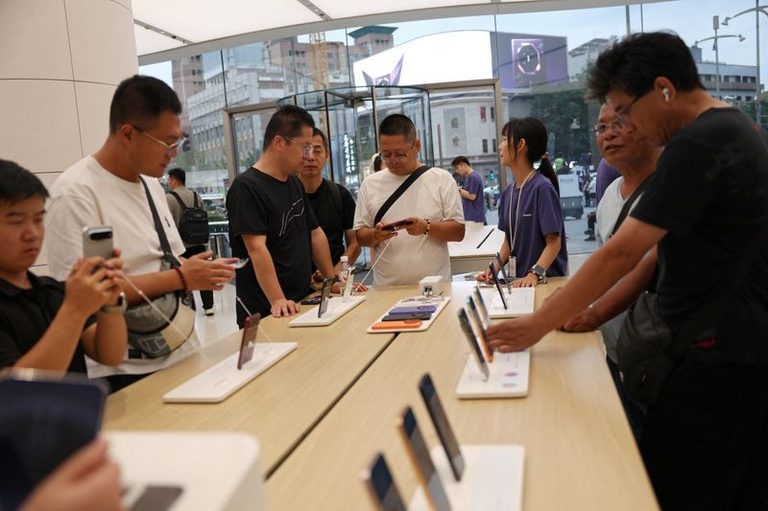
China’s smartphone market showed a sharp contraction in the third quarter of 2024, according to research firm IDC. Total shipments fell 15.4% from a year earlier, reaching 57.9 million units. The decline reflects weaker consumer spending and higher component costs that have pressured manufacturers and shoppers alike.
Huawei leads with growth amid a shrinking market
Huawei emerged as the sole major vendor to record double‑digit growth. The company shipped 12.2 million phones, capturing a 21% share of the Chinese market – the highest among all brands. IDC attributes Huawei’s performance to a broad product lineup and modest price increases, which helped the firm extend its momentum despite the overall downturn.
Apple and other rivals feel the squeeze
Apple held second place with a 17.8% market share, but its shipments fell 4.3% year‑over‑year. IDC noted that while Apple’s new iPhone models sold better than expected, a reduced model count this year limited its overall volume.
Domestic competitors Oppo, Vivo and Xiaomi all posted sizable declines, with shipments dropping 17.6%, 24.9% and 20.4% respectively. The slide underscores the challenges Chinese manufacturers face as they pass higher component costs – especially for memory chips – onto consumers, driving up retail prices at a time when demand is softening.
Industry outlook
Arthur Guo, senior analyst at IDC, said the market’s contraction is tied to “weak consumer spending” and “rising prices for memory chips and other components.” He added that vendors have been forced to raise retail prices, which further dampens demand.
IDC also highlighted Honor as the only leading brand that managed to grow shipments from the previous quarter, suggesting a possible rebound for the company. However, the broader trend points to a challenging environment for smartphone makers in China as they navigate cost pressures and a cautious consumer base.
What this means for consumers
Higher device prices are likely to persist in the short term, given the ongoing cost pressures on manufacturers. Shoppers may see fewer promotional discounts and a slower rollout of new models, especially from brands that are trimming their product lines to manage costs.
For businesses that rely on mobile devices – from retailers to logistics firms – the slowdown could translate into delayed upgrades and a tighter budgeting environment. Nonetheless, Huawei’s strong market share indicates that a well‑positioned product portfolio can still capture growth even when the overall market contracts.
Looking ahead
IDC will continue to monitor the Chinese smartphone market through the fourth quarter and into 2025, tracking how manufacturers adjust pricing strategies and product offerings in response to consumer sentiment and component cost trends.
Original reporting: Appleton, WI News Feed (HLL/CB) — read the source article.